$F
F Covered Call: 16.8% Annualized
Get every trade in your inbox. Free newsletter - one email per new idea, one per status change. Subscribe free
| Action | Qty | Expiry | Strike | Type | Premium |
|---|---|---|---|---|---|
| Buy | 100 | - | - | Stock | $11.98 |
| STO | 1 | Mar 19, 2027 | 10.00 | Call | $2.38 |
The trade (order placed Oct 12, working GTC):
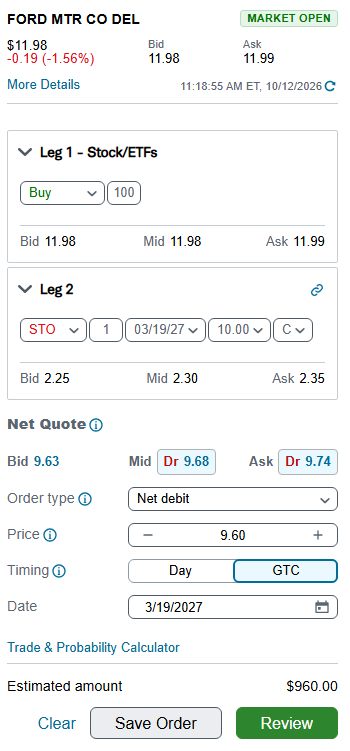
- Buy 100 shares of Ford (F) at $11.98
- Sell to open the Mar 19, 2027 $10 call
- Net debit: $9.60/share ($960)
The math:
- Called away at $10: $0.40/share price gain
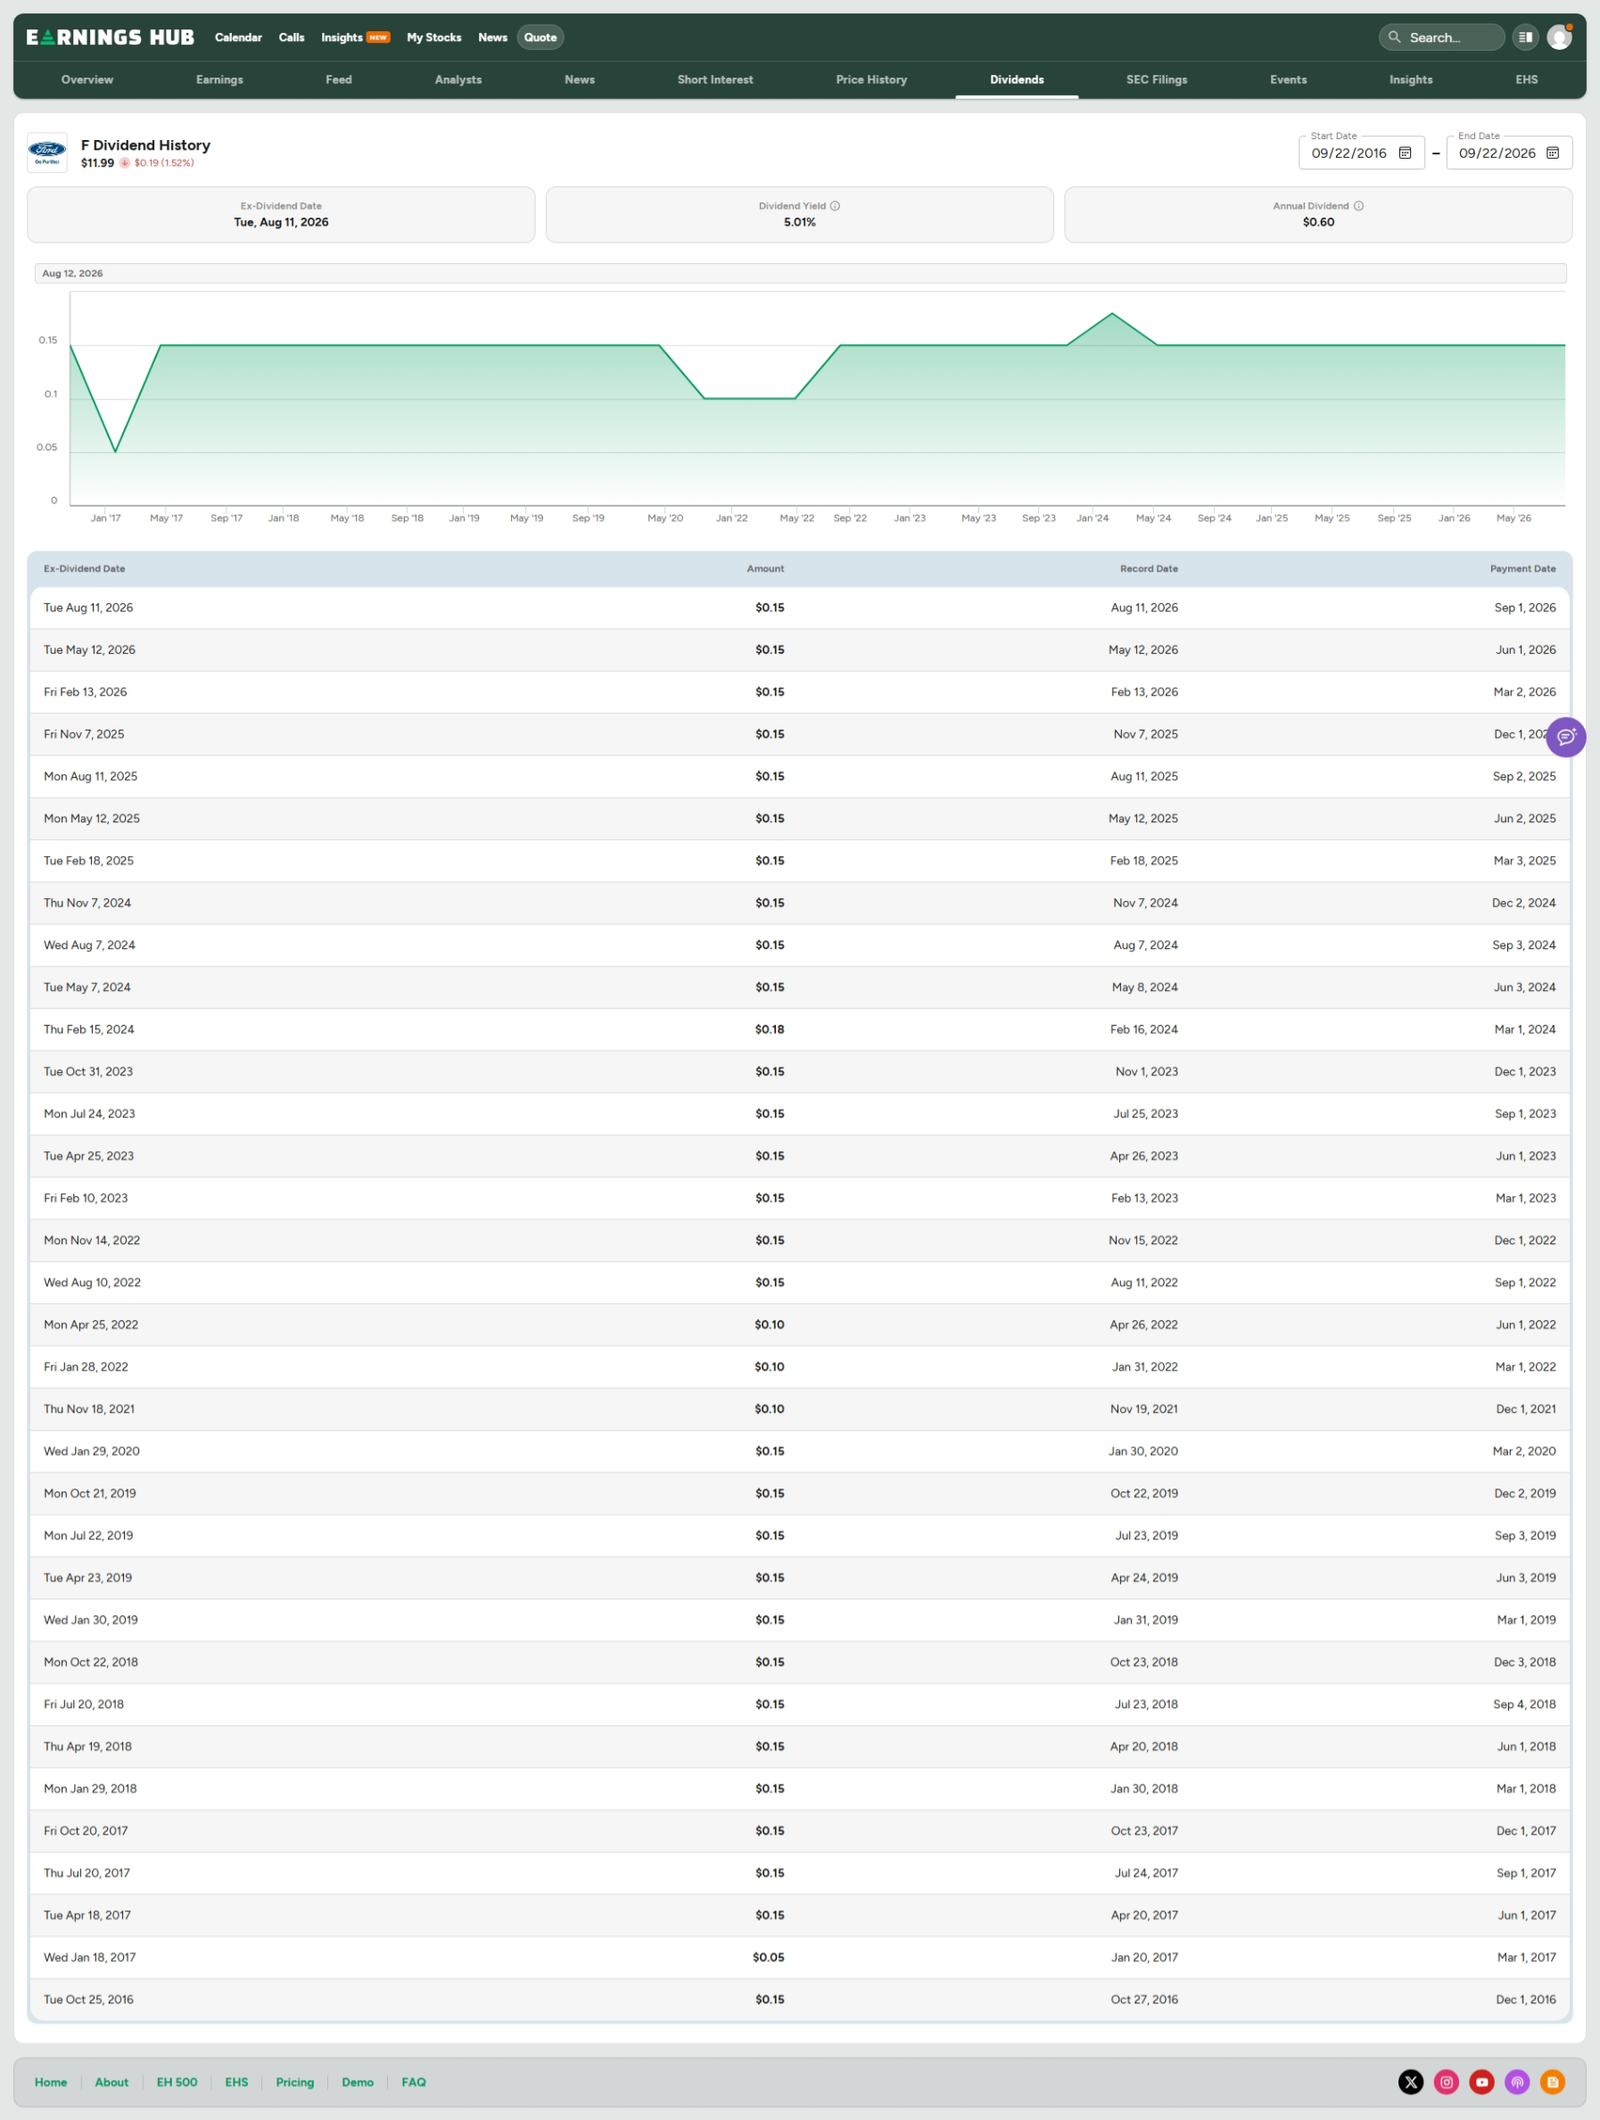
- Plus two $0.15 quarterly dividends (Nov + Feb): $0.30
- Total: $0.70/share = 7.3% in 158 days → 16.8% annualized
- Deep in-the-money (strike 16.5% below the stock): $2.38 premium banked, $9.60 breakeven - F can fall 19.9% before losing a dollar. Max loss $9.60/share vs $11.98 owning it outright.
Why this trade, why now:
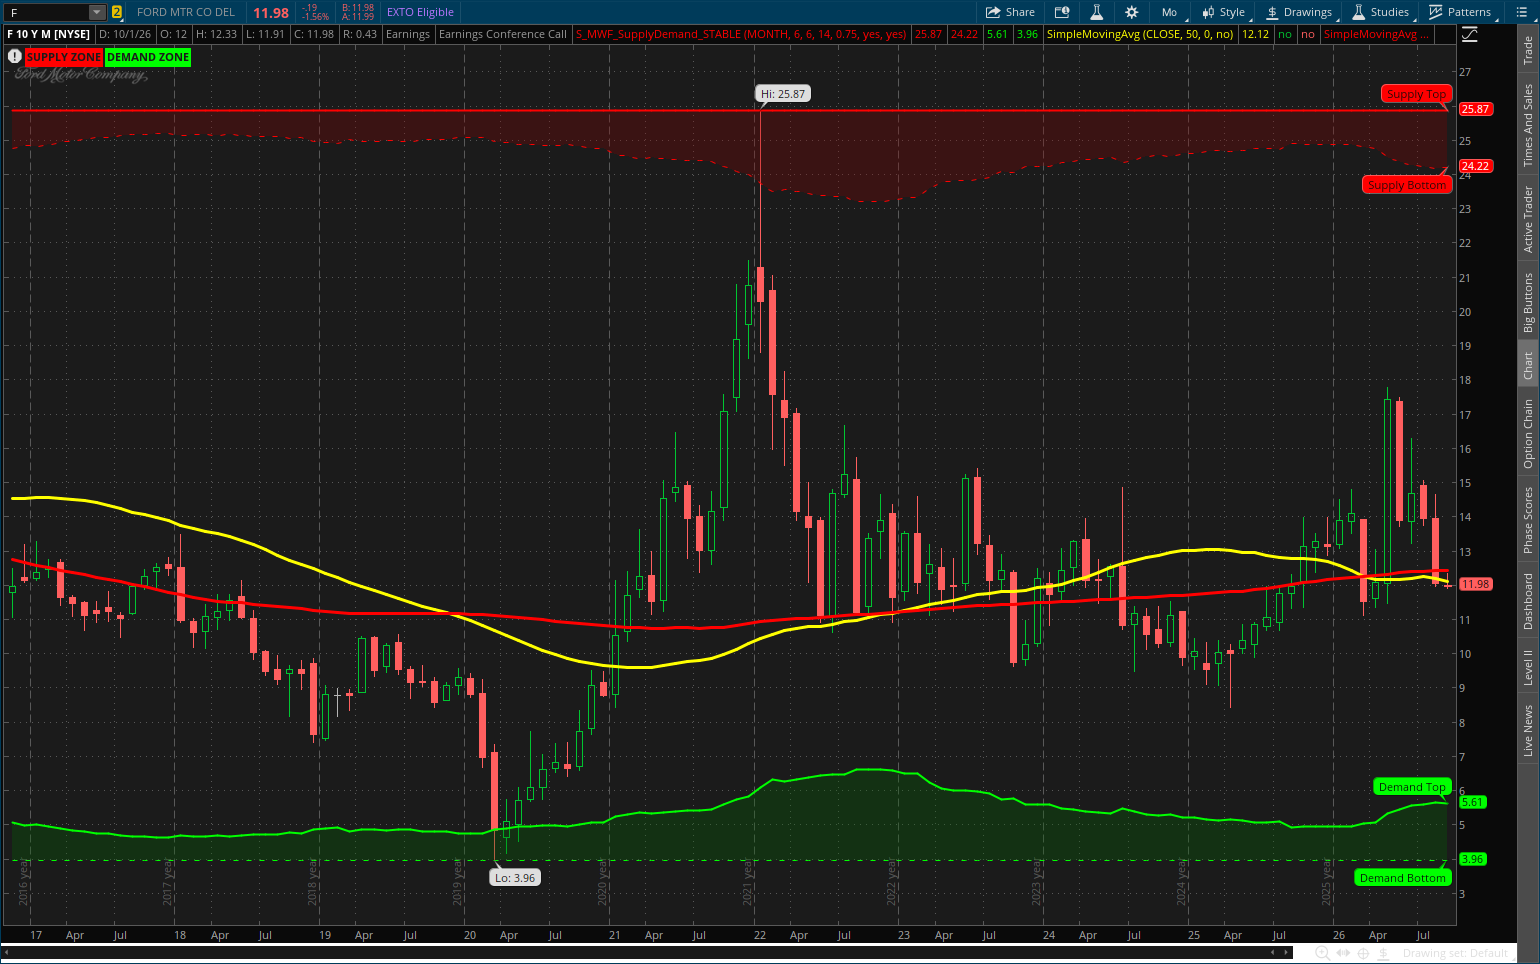
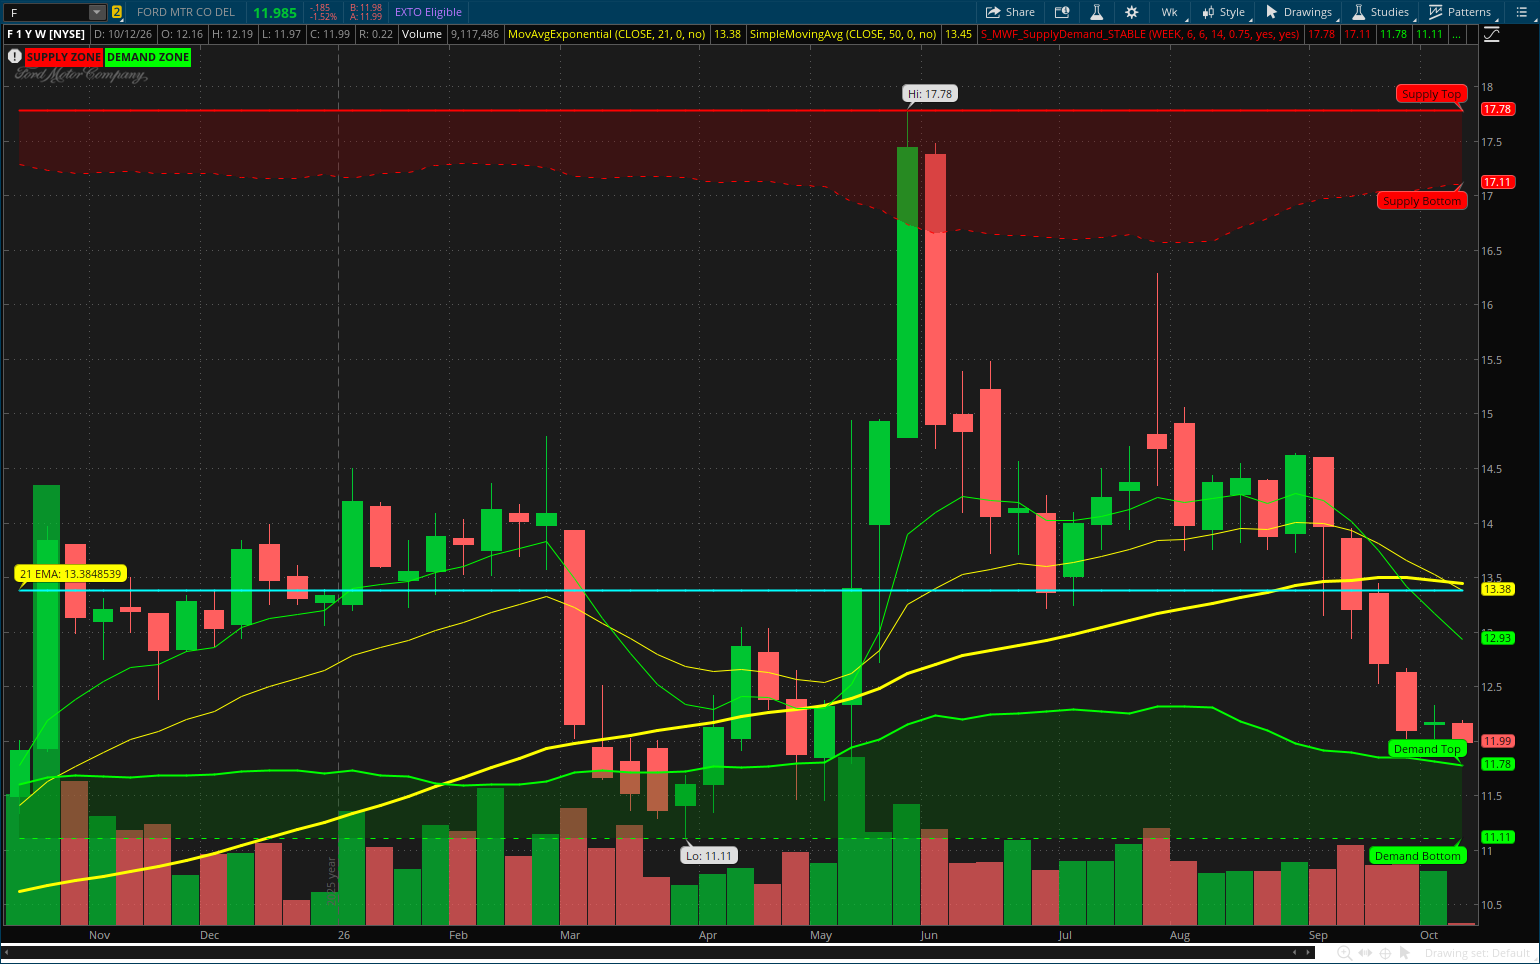
F lost ~13.5% in the past month and is sitting right on the weekly demand zone ($11.78-11.11). The tape is full of priced-in bad news: the F-150 supplier disruption hit Q3 wholesales (resolved, per CEO Farley), August sales fell 10.3%, Hyundai is set to outsell Ford in the US for the first time ever in Q3, and UBS cut its price target to $15 last week. The 5% dividend yield pays us to wait, and the two quarterly dividends add ~7 points to the annualized figure.
The risks, plainly:
- Upside is capped at $10. If F snaps back to $14-15, we keep our $0.40 and watch the rest go by.
- Below $9.60, losses accrue like owning the stock - just from a $2.38 lower starting point.
- Early-assignment risk ahead of the February ex-div if the call’s time value decays below $0.15 - we’d lose the second dividend.
- This is a trade, not a balance-sheet endorsement: Ford carries debt ~340% of market cap with an LTM operating loss.
Order placed Oct 12, working GTC - not yet filled.